11 Accounts Receivable Metrics That Actually Matter
Quick Summary
- Split your metrics into two jobs: report and act on. Most teams get this backwards, running stand-ups on DSO and never looking at right-party-contact rate
- Report metrics are portfolio-level and financial. DSO, turnover, and total AR give trend and context for the board, and rarely tell you what to do this week
- Act-on metrics are account-level and behavioral. Aging movement, promise-kept rate, and right-party-contact rate each point at a specific account and a specific next move
- Every metric misleads in a specific way. DSO moves with sales timing, averages hide the shape of the book, and promise-kept rate only counts promises someone logged
- ADD and the BPDSO gap are one metric, not two. ADD = DSO − BPDSO, the collectable slack in your book
- If you run the team on one number, make it CEI. It's less distorted by sales timing than DSO, though not undistorted
- Act-on metrics improve when you fix the upstream work, not when you chase harder
Which AR metrics to report and which to act on
Most AR dashboards are full of numbers that get reported up and acted on by nobody. A useful metric changes a decision, so the test worth applying is simple: which of these numbers changes what someone does this week?
Split them into two groups.
- Metrics to report are portfolio-level and financial. They're the view from the ridge, good for trend and context at board level, and they rarely tell you what to do. DSO lives here.
- Metrics to act on are account-level and behavioral. These are the tracks on the ground, pointing at a specific account and a specific next move. Right-party-contact rate and promise-kept rate live here.
Teams get this backwards constantly. They run stand-ups on DSO, which nobody in the room can influence this week, and never look at right-party-contact rate, which is immediately actionable.
The 4 metrics to report
1. Days Sales Outstanding (DSO)
DSO measures the average number of days it takes to collect after a sale.

DSO = (average accounts receivable ÷ total credit sales) × number of days in the period
Say your average AR over a quarter is $300,000, credit sales are $900,000, and the period is 90 days. DSO is (300,000 ÷ 900,000) × 90, which works out to 30 days.
DSO is the most-quoted metric in AR and the most misleading. It gets distorted by sales timing and revenue mix, so a move in DSO often tells you nothing about collections effort. A strong late-quarter sales month pushes it up even when the team collected exactly as well as before.
A rolling twelve-month DSO reduces the seasonality distortion, though it doesn't remove mix effects. Useful as a long-run trend, weak as a this-week signal. Report it, and don't run the team on it.
For benchmarks and levers, see the full guide on days sales outstanding.
2. Accounts receivable turnover ratio
This ratio shows how many times you collect your average receivables over a period.

AR turnover = net credit sales ÷ average accounts receivable
Using the same numbers, $900,000 divided by $300,000 gives a turnover of 3 for the quarter. Divide the days in the period by the ratio and you get turnover in days, which lines up with DSO.
It's the same information as DSO, inverted, and it misleads the same way. Fine for benchmarking and board decks, weak as an operational lever. The full turnover guide covers the formula, a worked example, and the calculation mistakes that quietly inflate it.
3. Total AR
Total AR is the size of your book. It's a decent health snapshot and a weak action trigger, because it says nothing about quality.
The way it misleads is by treating every dollar alike. A dollar at 15 days and a dollar at 95 days count identically, even though one is nearly certain to arrive and the other is odds-against.
4. Percent current
Percent current is the share of your receivables sitting inside terms.
A big book that's 95% current is healthy. A smaller book that's 60% current needs work. Read it alongside total AR.
Its blind spot is concentration. A healthy percent-current figure can coexist with a small number of large, badly aged balances that are quietly heading for write-off. Percent current is a volume measure, and write-offs are a value problem.
The 7 metrics to act on
5. Aging at the account level
The summary tells you the size of the problem. The detail, which accounts are sliding from 30 to 60 to 90, tells you where to spend the next hour.
An account that just crossed from current into overdue is the single best use of a collector's next hour, because collectability falls steeply with age, as covered in the process guide.
The trap is reading the buckets as static. Two books can show identical bucket totals while one is stable and the other is deteriorating fast underneath. Only the movement tells them apart, which is why you read the tracks rather than the totals.
6. Collections Effectiveness Index (CEI)
CEI measures how much of your available receivables you actually collected in a period, as a percentage.
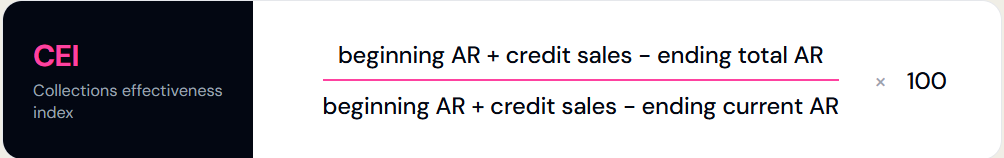
CEI = [(beginning AR + credit sales − ending total AR) ÷ (beginning AR + credit sales − ending current AR)] × 100
A score near 100% means collections are working. A rising CEI means you're converting receivables to cash efficiently. A falling CEI with flat DSO points at trouble DSO is hiding.
If you run the team on one number, this is the better one. It's less distorted by sales timing than DSO, though not undistorted, since it still carries the period's credit sales. It's also sensitive to the window you pick, so one large collection landing just inside or outside the period can swing it.
The collection effectiveness index guide walks through the math.
7. Best Possible DSO and Average Days Delinquent
These two are the same lever, named twice, and a lot of content wrongly treats them as separate metrics. State the identity once and it becomes one of the most action-guiding numbers in AR.
Best Possible DSO is the DSO you would have if every current invoice were collected exactly on terms.
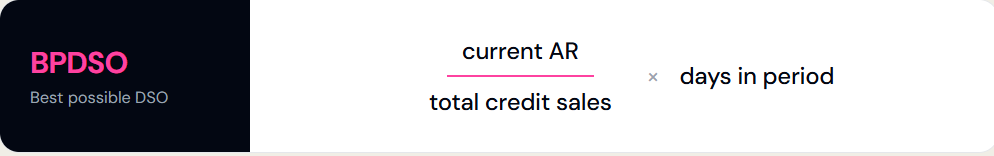
BPDSO = (current AR ÷ total credit sales) × number of days
Average Days Delinquent is the difference between the two.

ADD = DSO − BPDSO
ADD is your collectable slack, the days of DSO that better execution wins back. A rising ADD points at collections, since your terms haven't moved, and almost nobody reports it.
Two ways it misleads. A few very large, very late invoices can drag the average up and hide an otherwise healthy book, so look at the distribution before reacting to the mean. And BPDSO assumes your terms are sensible, so a business on net 90 can show a flattering number while carrying a working capital problem no amount of collecting will fix.
More in the guide on average days delinquent.
8. Promise-to-pay kept rate

Promise-kept rate = kept promises ÷ total promises, tracked per account
A leading indicator that moves weeks before DSO does. An account with a falling kept rate is telling you something is wrong long before the aging report catches it.
Its blind spot is capture. It only measures promises somebody logged, so a team that takes verbal commitments and never records them gets a flattering number built from the few promises formal enough to write down.
9. Right-party-contact rate
The share of your outreach that actually reaches a real person who can pay.
If this is low, no cadence tuning matters. You're emailing the void, and the aging is a data problem wearing a collections costume. That makes it one of the most directly actionable numbers you have, because it points straight at contact-data work.
Define "right party" tightly before you measure it. Left loose, the number drifts toward meaning "someone replied," which is a different and much weaker claim.
10. Dispute rate and dispute cycle time

Dispute rate = disputed value ÷ total AR

Cycle time = average days from raised to resolved
A rising dispute rate points at invoicing or delivery problems upstream, so it costs you twice: the held cash now, and the repeat disputes until you fix the source.
This pair misleads in a counterintuitive way. When a team gets better at logging disputes properly, the measured rate goes up, so an improving process can look like a deteriorating one for a quarter or two. Read the rate alongside cycle time.
11. Bad-debt write-off rate
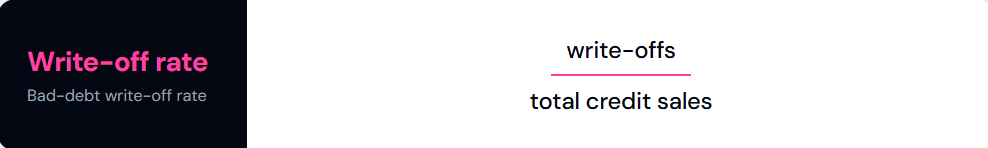
Write-off rate = write-offs ÷ total credit sales
The ultimate scoreboard, lagging but real, and the number your allowance for doubtful accounts is trying to predict.
Because it lags, it misleads by arriving late. By the time the write-off rate moves, the failures that caused it happened months earlier, which is exactly why the leading indicators above earn their place.
How to choose which AR metrics to track
Most AR dashboards track everything and drive nothing. Keep the set small, and start from the problem you're trying to fix.
Match the metric to the problem
Pick the number that speaks to your specific pain:
- Slow payments overall: DSO for the trend, CEI and ADD for whether collections is working
- A long tail that never gets worked: account-level aging movement and right-party-contact rate
- Disputes eating your cash: dispute rate and dispute cycle time
- Chasing people who already paid: cash application backlog and unapplied cash
If a metric maps to no problem you have, drop it.
Balance efficiency and quality
Speed metrics show how fast you collect. Quality metrics show whether the process is healthy underneath. Track both:
- Efficiency: DSO, AR turnover, ADD
- Quality: CEI, dispute rate, promise-to-pay kept rate
Track only speed, and you push hard collections that damage relationships. Track only quality, and you miss a slow slide in cash.
See how Lunos solves this
Every metric on this page improves the same way, with consistent follow-up and records that are actually live. Lunos works every account on your ledger and logs every promise and reply, so your act-on metrics are real numbers instead of estimates.
How to improve your AR metrics
Improvement comes from a handful of levers. Each moves a specific act-on metric, and most tie straight back to your process and the automation behind it:
- Clean up your contact data to move right-party-contact rate. Verify billing contacts and refresh records when a customer's AP gets outsourced, because no cadence works if you never reach a real person
- Reach out earlier to move DSO, ADD, and aging. A pre-due confirmation and a day-one reminder beat a firm notice at 60 days, and a steady collection cadence that works accounts while they're young is the cheapest cash you'll recover
- Resolve disputes faster to move dispute cycle time and CEI. Pull the invoice from the chase, give it an owner, track days-to-resolve, and fix the upstream invoicing or delivery cause behind a rising dispute rate
- Tighten cash application to move your false-past-due rate. Faster, accurate cash application stops you chasing customers who already paid and makes your aging report honest
- Put automation behind the levers to move all of them at scale. The levers are simple, but doing them on every account every day is where AR automation earns its place
The pattern holds. Act-on metrics improve when you fix the upstream work, not when you chase harder.
FAQs
What is a good DSO?
It depends on your terms and industry. As a rule, a DSO close to your standard terms is healthy. Bill net 30 and sit near 30, and you're collecting on time. Watch the trend more than the single figure.
What is the most important accounts receivable metric?
If you track one, make it CEI. It measures whether your collections effort is actually turning receivables into cash, and it's less distorted by sales timing than DSO. Rising CEI means the process is working.
What is the difference between DSO and AR turnover?
They measure the same thing from two angles. DSO is the average number of days to collect. AR turnover is how many times you collect your average receivables in a period. Turnover in days lines up with DSO.
What is the difference between ADD and the BPDSO gap?
There's none. Average Days Delinquent is DSO minus Best Possible DSO, which is the same calculation. A lot of content presents them as two metrics, and treating them as one makes the number easier to act on.
The view from the ridge won't show you which account is slipping
Lunos gives you both, with real-time visibility into promises, at-risk accounts, and payment intent across the whole book. Book a demo to see your metrics move.